


Decoding Commercial Bank Q1 Report: Industry Profit Crosses 19 Arba
Mon, Nov 2, 2026 8:29 PM on Financial Analysis, Highlight News, Company Analysis, Stock Market, National,

Currently, there are 20 operating Class 'A' commercial banks in Nepal, out of which 19 are listed on the Nepal Stock Exchange (NEPSE) with state owned Rastriya Banijya Bank Limited (RBBL) remaining unlisted.
In this parameters analysis of Q1 2083/84 unaudited report, we evaluate the performance of these commercial banks across five key parameters: Net Profit, Distributable Profit Per Share (DPS), Earnings Per Share (EPS), Price-to-Earnings (P/E) ratio, and Non-Performing Loans (NPL).
Net Profit:
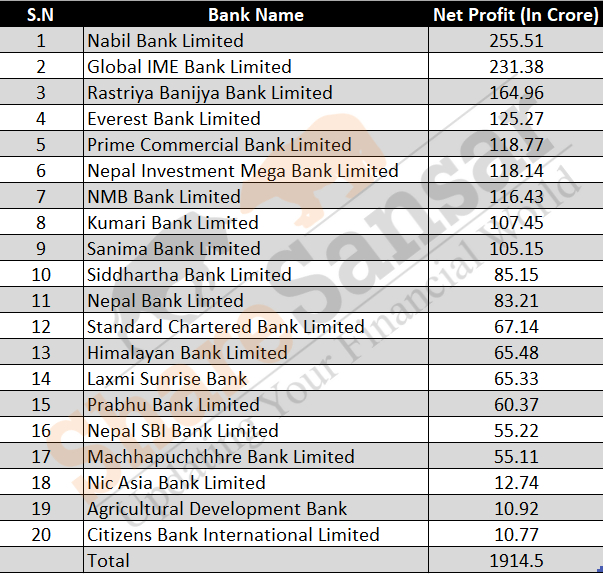
The total industry net profit across all 20 commercial banks stands at Rs. 1,914.50 Crore. The top 3 highest performing banks are led by Nabil Bank Limited at Rs. 255.51 Crore, followed by Global IME Bank Limited at Rs. 231.38 Crore, and Rastriya Banijya Bank Limited at Rs. 164.96 Crore.
Conversely, the lowest 3 performing banks at the bottom of the sector are Nic Asia Bank Limited at Rs. 12.74 Crore, Agricultural Development Bank at Rs. 10.92 Crore, and Citizens Bank International Limited at Rs. 10.77 Crore.
Distributable Profit Per Share (DPS):
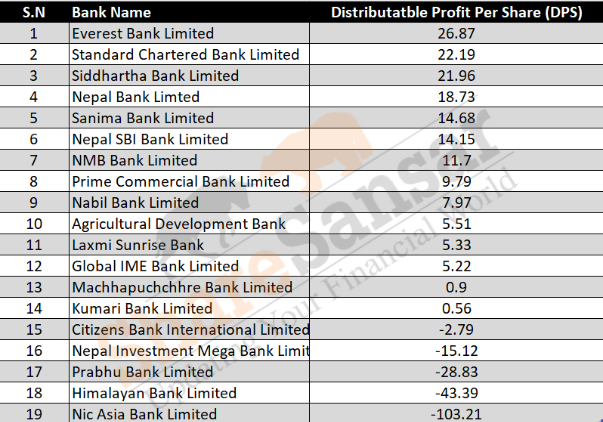
The Q1 Distributable Profit Per Share (DPS) analysis across 19 listed commercial banks highlights a sharp structural divide in dividend paying potential. Everest Bank Limited leads the industry with a DPS of 26.87, closely followed by Standard Chartered Bank Limited 22.19 and Siddhartha Bank Limited 21.96.
On the opposite end, heavy regulatory provisioning, non-performing loan adjustments, or accumulated losses have dragged five banks into negative territory, anchored by Prabhu Bank Limited (-28.83), Himalayan Bank Limited (-43.39), and NIC Asia Bank Limited (-103.21). This creates a clear distinction between institutions capable of delivering immediate dividend capacity to shareholders and those focused primarily on balance sheet repair.
Note: DPS is non-annualized
Earning Per Share (EPS):
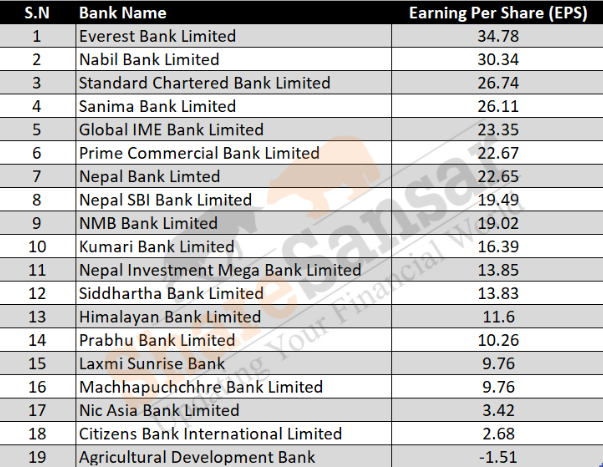
The Q1 Annualized Earnings Per Share (EPS) figures demonstrate significant operational efficiency variances across the 19 listed commercial banks. Everest Bank Limited leads the industry with an annualized EPS of Rs. 34.78, closely followed by Nabil Bank Limited Rs. 30.34 and Standard Chartered Bank Limited Rs. 26.74.
At the bottom spectrum, profitability remains severely strained for Nic Asia Bank Limited Rs. 3.42 and Citizens Bank International Limited Rs. 2.68, while Agricultural Development Bank posted the lowest performance as the only institution with a negative EPS of Rs. -1.51.
Note: Preference Share Dividend is adjusted while calculating EPS.
Price to Earning Ratio (P/E):
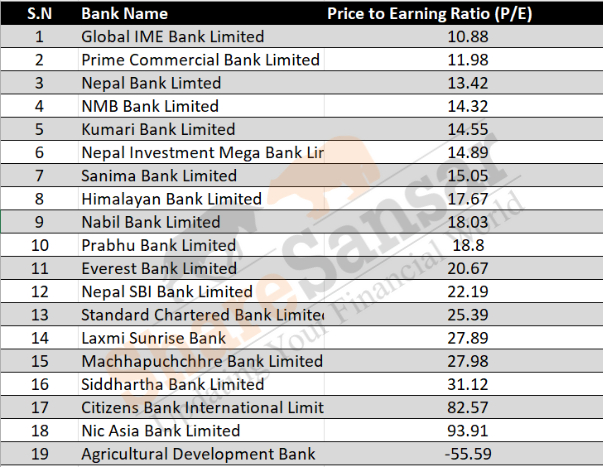
The Q1 Price-to-Earnings (P/E) ratio analysis reveals a wide dispersion in valuation multiples across the 19 listed commercial banks. Global IME Bank Limited presents the lowest P/E ratio at 10.88, closely followed by Prime Commercial Bank Limited 11.98 and Nepal Bank Limited 13.42, indicating relatively attractive valuation levels based on current earnings.
Conversely, Banks experiencing compressed earnings face heavily inflated or distorted multiples, led by Citizens Bank International Limited at 82.57 and Nic Asia Bank Limited at 93.91, while Agricultural Development Bank registers a negative P/E of -55.59 due to its negative earnings per share.
Non Performing Loan (NPL):
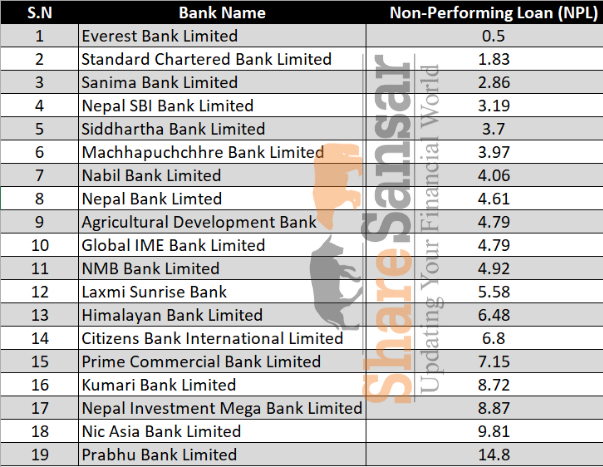
The Q1 Non-Performing Loan (NPL) figures reveal significant credit risk divergence across the 19 listed commercial banks. Everest Bank Limited maintains superior asset quality with an industry leading low NPL of 0.50%, followed by Standard Chartered Bank Limited 1.83% and Sanima Bank Limited 2.86%.
In contrast, credit quality remains heavily strained at the lower end, anchored by Nepal Investment Mega Bank Limited 8.87%, NIC Asia Bank Limited 9.81%, and Prabhu Bank Limited at a steep 14.80%.
Elevated bad loans across these bottom tier institutions continue to necessitate aggressive provisioning, directly suppressing their profitability and dividend capacity.
Conclusion:
Across the 20 commercial banks analyzed across Net Profit, DPS, EPS, P/E ratio, and NPL, Everest Bank Limited and Standard Chartered Bank Limited emerge as the clearest balance sheet outperformers, combining top tier EPS Rs. 34.78 and Rs. 26.74 and industry leading dividend capacity DPS of 26.87 and 22.19 with exceptional credit quality anchored by low NPLs of 0.50% and 1.83%, respectively.
While volume leaders like Nabil Bank Rs. 255.51 Crore and Global IME Bank Rs. 231.38 Crore dominate absolute net profitability with Global IME offering an attractive P/E multiple of 10.88 the broader sector exhibits severe operational stratification.
At the opposite spectrum, heavy non-performing loan burdens at institutions such as Prabhu Bank 14.80% NPL and NIC Asia Bank 9.81% NPL have triggered massive regulatory provisioning, collapsing their distributable profits to deep negative figures -28.83 and -103.21 DPS and inflating valuation multiples to unsustainable levels.
Ultimately, the Q1 data demonstrates that market performance is sharply bifurcated between well capitalized banks with clean asset bases and recovery phase institutions constrained by credit impairment.

